by Philip von der Goltz
Coffee Market: What Happened Last Week – and Where Are We Heading?
The sweet irony of fate. That was my thought today as I read the news. If diesel prices remain at record levels, they could accelerate precisely what some of the political figures responsible find least appealing: the shift towards alternative energy sources. President Trump, Iran's rulers, Putin and President Zelensky thus become, quite incidentally and entirely unwillingly, green activists. Who would have thought?
Commodity traders have a fitting expression: the cure for high prices is ... drumroll ... high prices. History has proven this rule often enough. When oil, diesel and petrol stay expensive for long, the incentive to develop and deploy alternatives grows.
Add a geopolitical landscape in which self-sufficiency increasingly matters more than international co-operation. The energy squeeze is therefore unlikely to be solved simply by more tankers leaving the producing countries. At the same time, modern societies' appetite for energy will not shrink in the years ahead. Alternatives are needed. And high prices make them more attractive.
In the coffee world, the players and their motives are fortunately different. The economic mechanism, however, is strikingly similar.
The high prices of the past three to four years have encouraged coffee producers to invest consistently in their farms. Good husbandry and enough water, whether from irrigation or rain, lead to higher yields. Brazil is now showing what that can deliver. The country is bringing in a record crop, and shipments are rapidly gathering pace. August was already a record month, and September looks set to establish a record of its own.
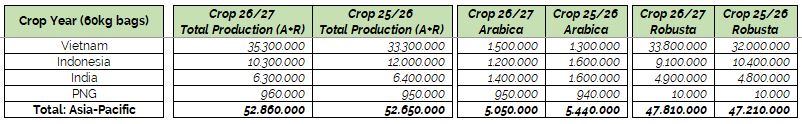
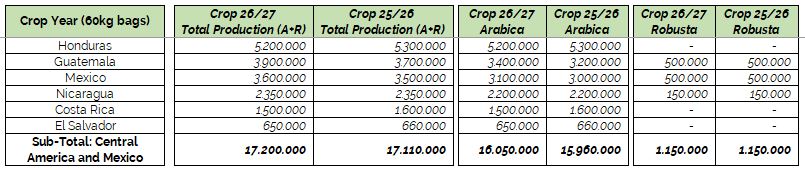
Vietnam's new harvest is also just around the corner. Early estimates are encouraging: experts expect more than 35 million bags. Investment has also taken place across other producing countries. In Central America's lower-lying regions, harvesting has already begun. Colombia is approaching its main harvest, although it is still grappling with the aftermath of the powerful earthquake and the resulting damage to its infrastructure.
This is bringing some relief to the coffee futures markets. Certified stocks remain extremely low, but the outlook for the coming months is becoming more reassuring: there is enough coffee in the pipeline.
Based on our current assessment, the slowly developing super El Niño is unlikely to change that picture significantly – at least in the short term. Its potential effects come against a backdrop of higher production and somewhat subdued consumption. In this setting, we do not expect it to exert sustained upward pressure on prices.
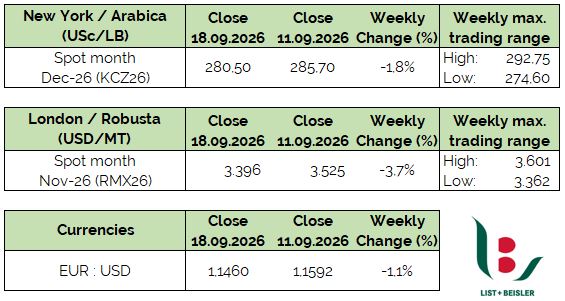
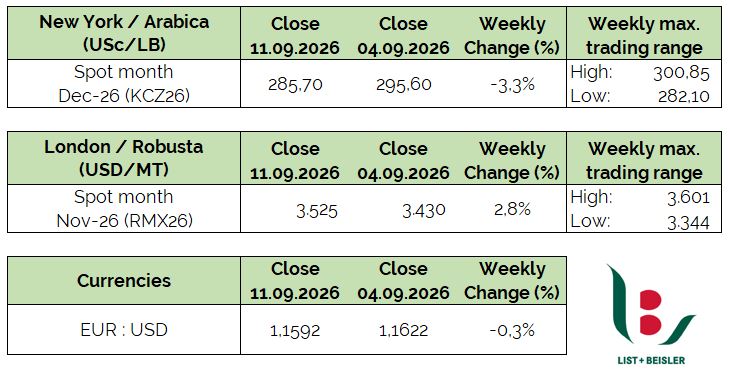
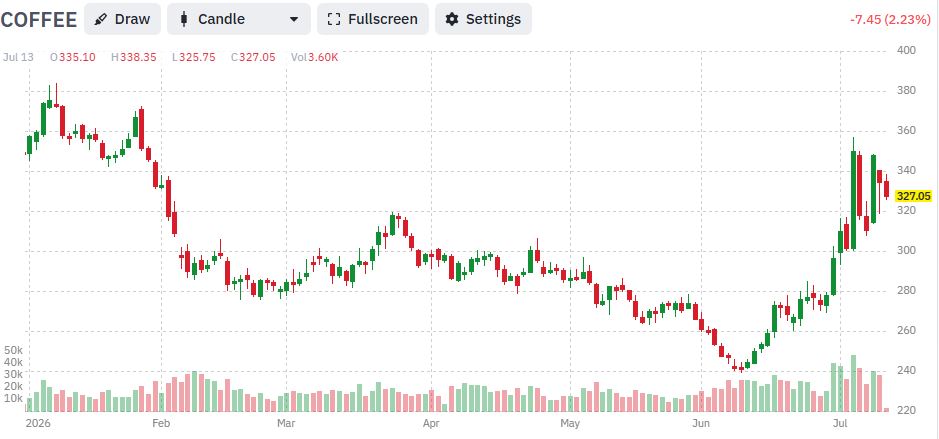
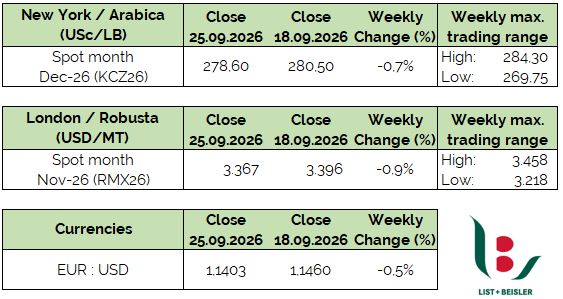
The New York and London markets reflected that assessment last week. On Wednesday, both Arabica and Robusta reached fresh three-month lows. By the end of the week, however, prices were almost unchanged from the previous week. Trading volumes remained thin in both markets. Volatility, too, stayed within modest bounds compared with the swings of the recent past.
An uneventful trading week. After the past few months, that counts as good news.
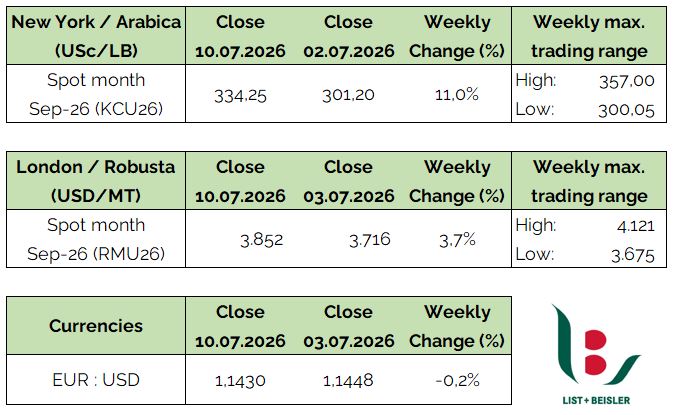
The following table summarises the key coffee market data. We update it weekly:
News from Origin: Brazil, Colombia, and Peru
Brazil
All eyes are currently on Brazil, whether for politics or coffee. Brazilians go to the polls on October 4, with the frontrunners being Lula da Silva, who previously served two terms as Brazil's president, and Flávio Bolsonaro, son of former President Jair Bolsonaro. Flávio wants to bring Brazil closer to the US and away from China. Lula, on the other hand, is campaigning against this, vowing to stand up to Trump and accusing him of interfering in Brazil's elections.
As for coffee, the forecast for a record harvest remains unchanged. CONAB (Brazil's National Supply Company) projects production at 67.6 million bags, an increase of 19.6% compared with the previous crop. Brazil also recorded its highest August coffee exports, up 31% to 4.1 million bags, according to Cecafé (Brazilian Coffee Exporters Council).
Meanwhile, the 2026/2027 harvest is nearly complete, with Brazilian coffee continuing to reach the market and add to global supplies. Arabica trading has slowed, and availability of higher-quality and certified coffees is getting tighter. Producers also seem reluctant to sell at current lower NY prices.
Conilon (Robusta) is also trading in small volumes, although stocks are available.
As for the upcoming 2027/2028 crop, forecasts also point to a good harvest, with steady rainfall favoring the flowering period. As in the rest of the world, however, there is some concern about the possible negative effects of El Niño in the coming months.
On the logistics side, operations remain challenging. Demand for freight is strong, with shipping lines fully booked several weeks in advance.
Colombia
The prospect of a stronger El Niño is also causing concern in Colombia. Forecasts point to below-normal rainfall in the coming months, creating uncertainty about the development, yield, and quality of the crop ahead of the main harvest. For now, the impact is limited; the most critical period is expected toward the end of the year and into January 2027.
The Mitaca (fly crop) is nearly complete, and coffee flow is good. Trade has been slow as producers are reluctant to sell at current market prices.
According to Colombia's National Coffee Growers Federation, the August earthquake did not affect harvest volumes, despite affecting parts of southeastern and central Colombia. Higher temperatures and a lack of rain associated with El Niño are considered the greater risk to the upcoming harvest.
Following the earthquake, operations at the port of Buenaventura have resumed.
Peru
Weather conditions in northern regions, including Cajamarca, Piura and Amazonas, are hot and dry, supporting picking and drying activities. The harvest is still ongoing, with around 20% of the crop yet to be collected in high-altitude areas.
As in Colombia, producers are holding back their stocks due to lower prices on the New York C market. Demand is high, and with availability particularly low, local prices are increasing.
Coffee is being shipped normally from the port of Callao, although there are some delays. Fresh crop coffees from Peru has already arrived to our warehouses in Hamburg, take a look at them at our webshop