Coffee Market: what happened last week – and where are we heading?
By Philip von der Goltz
In uncertain times – and yes, that is precisely where we find ourselves – people look for ways to keep their hard-earned money safe.
Those fortunate enough to live in a country with a reasonably stable currency and a functioning financial system have plenty of options: bank deposits, shares, real estate, bonds or other investments. The only question is whom to trust with their money.
In many parts of the world, however, things are not quite so straightforward.
Where confidence in banks and currencies is limited, inflation and exchange-rate fluctuations can wipe out years of carefully accumulated savings in remarkably little time. What was a small fortune yesterday might barely cover the weekly grocery bill tomorrow.
So people look for alternatives. And they can be remarkably inventive.
Gold, art and property are traditional ways of preserving wealth. But what if you lack both the capital and the access needed to invest in these markets?
You invest in what you know. And sometimes, that happens to be coffee.
Before we get to that, a brief excursion into Brazilian economic history is in order.
In March 1990, Brazilian President Fernando Collor de Mello introduced a plan to combat hyperinflation that was as radical as it was consequential. The so-called Plano Collor included a measure to freeze a large proportion of private bank deposits and financial investments for 18 months.
Overnight, millions of Brazilians lost access to substantial portions of their savings.
Inflation initially fell, only to return with a vengeance. What followed was a severe recession, an acute liquidity crisis and a profound loss of confidence in the financial system.
For business owners, the consequences were particularly painful. Bills still had to be paid, employees needed their wages, and businesses had to keep operating. Agriculture was no exception. Anyone suddenly deprived of access to their own money had to find other ways of staying liquid.
Whether, and to what extent, this experience still influences the behavior of Brazilian coffee farmers today is difficult to establish. But it illustrates a fundamental problem: money in the bank is only a source of security if you can actually get your hands on it.
Which brings us back to coffee.
For a coffee farmer, the harvest is more than the result of a year's hard work. It is also an asset. And provided the coffee is stored properly, that asset can retain its value over time.
An old farming saying captures the idea rather neatly:
A farmer should always have three harvests: one in the field, one in the warehouse and one in the bank.
Easier said than done, of course. Not every farmer has sufficient storage capacity, and not everyone can afford to hold on to their crop for months. Those who need to service loans, pay employees or finance the next harvest need cash.
But farmers with adequate storage facilities and financial reserves enjoy one decisive advantage: they can afford to wait.
And that is what makes the situation in Brazil so interesting at the moment.
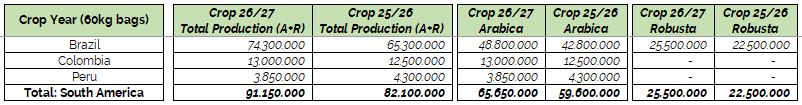
The 2026/27 harvest is expected to be among the largest in Brazilian history. It's estimated around 74 million bags. There should be no shortage of coffee.
Yet a large harvest does not necessarily mean that all that coffee immediately becomes available to the market.
Farmers decide for themselves when to sell. The exchange rate of the Brazilian real, expectations about future prices, financing costs and individual liquidity requirements all play an important role in that decision.
And then there is logistics.
Brazil has substantial coffee storage capacity. But between a bag of coffee sitting on a farm in Minas Gerais and a warehouse in Hamburg lie several thousand kilometres, multiple modes of transport, two ports and, more often than not, a fair number of delays.
The port of Santos, in particular, is under pressure from Brazil's enormous agricultural exports. Limited inland transport capacity, heavily utilized terminals and unreliable shipping schedules can put additional strain on supply chains.
At the same time, certified Arabica stocks on the New York exchange remain exceptionally low. Brazilian coffee is now arriving at the relevant warehouses, but not every bag delivered immediately becomes certified exchange stock.
The continued backwardation in the futures market also tells us that coffee available for prompt delivery commands a premium over coffee for later delivery. This does not necessarily mean there is a global shortage. Rather, it highlights just how important the timing of physical availability has become.
There is coffee, then. Plenty of it, in fact. Just not necessarily where it is needed.
And even the fastest trading algorithms cannot do much about that.
While millions of dollars change hands on the exchanges in milliseconds, physical coffee still has to make its decidedly analogue journey to the customer by truck, train and container ship.
For all our advances in digitalization, we have not quite reached the point where you can download a coffee NFT in the morning and brew it for breakfast.
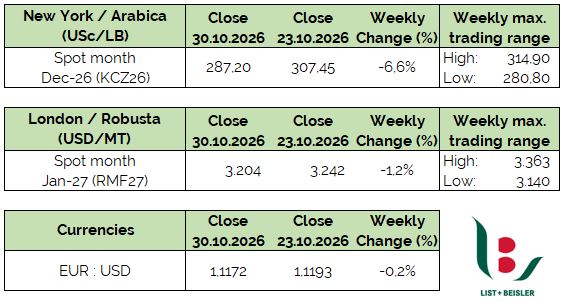
Meanwhile, trading on the coffee exchanges was lively enough last week.
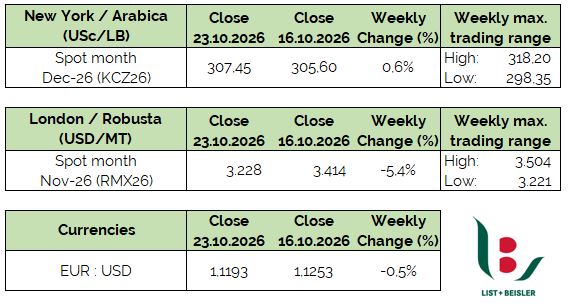
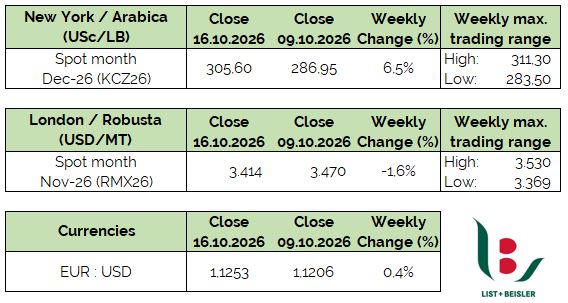
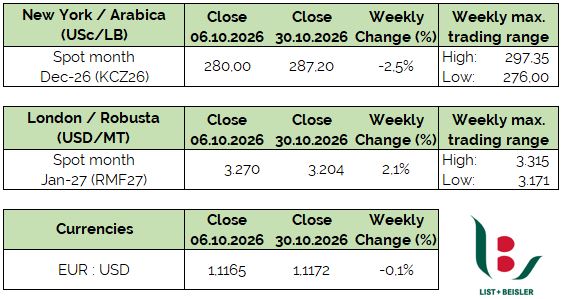
The December Arabica contract in New York (KCZ26) traded in a range of approximately 276 to 297 c/lb. On Friday, it headed into the weekend at 280.00 c/lb, representing a weekly decline of 2.5%, despite a modest recovery during Friday's session.
Robusta, by contrast, proved somewhat more resilient. The January 2027 contract (RMF27) closed in London at USD 3,270/MT, recording a weekly gain of approximately 2.1%.
Two coffee markets, two rather different weekly performances. And between them, a physical supply chain that remains largely unimpressed by the frantic movements of the exchanges.
Because, at the end of the day, one thing has not changed:
You can trade coffee in milliseconds. But you still have to deliver it.
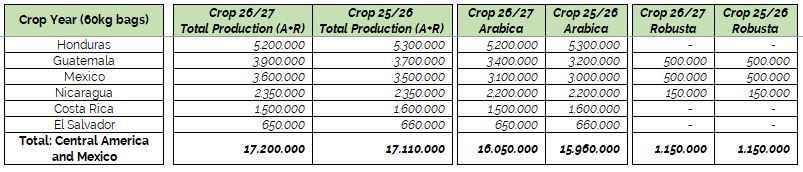
As usual, the following table contains the most relevant coffee market data. We update it weekly.
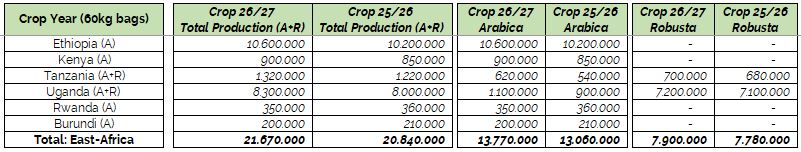
Origin News: Ethiopia, Kenya, Tanzania, Uganda
Ethiopia
Ethiopia's northern Tigray region remains under pressure, with ongoing tensions between the Ethiopian government and the Tigray People's Liberation Front (TPLF). Meanwhile, a separate dispute over control of areas along the border between the Oromia and Somali regions is raising further security concerns in the norther Ethiopia. As violence escalates, thousands of people from the border town of Moyale have fled to neighboring Kenya.
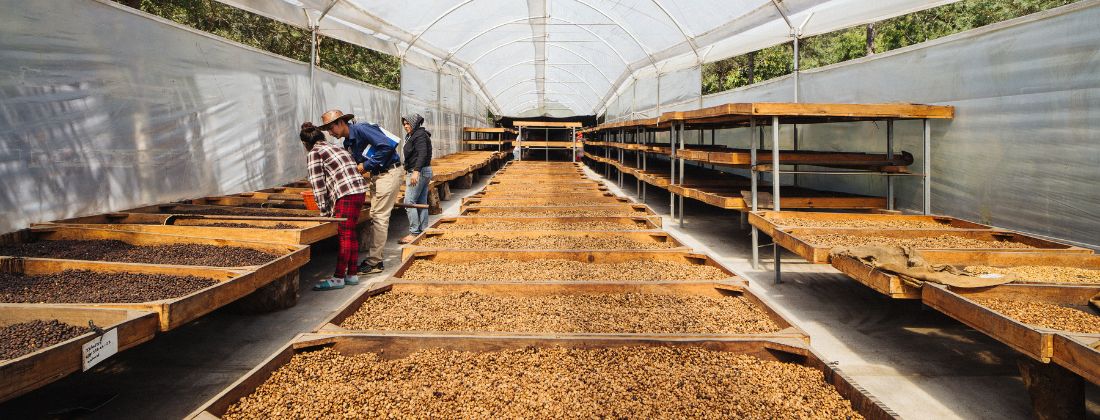
Ethiopia experienced above-average rainfall in October. While the rain is beneficial for coffee tree health, persistent wet conditions are making harvesting and processing particularly challenging in the southern regions. Harvesting has begun across the country's main producing areas and is expected to continue into early next year. We are now eagerly awaiting the first washed coffee samples to arrive at our lab and will keep you posted.
Cherry prices remain volatile. In western regions, prices have been rising and are now higher than in some southern areas, where drought in previous months has affected coffee quality. As the harvest progresses, demand is also gaining momentum.
Besides the well-known delays there are no significant updates from the Port of Djibouti.
Kenya
Rainfall has been recorded across all major coffee-growing regions, supporting the ongoing harvest. These conditions are accelerating harvesting activities, with the main crop now at its peak and approximately 50% complete. Dry mill operations are also picking up pace as increasing volumes of parchment coffee continue to arrive. Expectation for season are very positive. Farmers report healthy farms, with early indications of high volumes and good, consistent quality.
Coffee auctions are ongoing at the Nairobi Coffee Exchange, with strong demand from exporters.
The Port of Mombasa continues to operate at a slow pace, with occasional shortages of food-grade containers.
Tanzania
Coffee-producing regions have experienced some short rains over the past few weeks. In the southern highlands of Mbeya and Mbinga, these rains have triggered flowering, offering an early glimpse of next year's crop potential. Weather conditions are being closely monitored, as a potential Super El Niño could bring heavier rainfall and create additional challenges at farm level.
The Arabica harvest is largely complete, and dry mills continue to operate at full capacity. However, parchment deliveries are gradually slowing down. Total production volumes of both Arabica and Robusta for the 2026/27 season are expected to be slightly higher than in the previous season.
Availability is becoming increasingly limited, keeping differentials firm.
The Port of Dar es Salaam continues to experience some delays.
Uganda
Following a prolonged period of hot and dry weather, rainfall is becoming more frequent across Uganda's coffee-growing regions. While the rain is supporting crop development, it is also slowing down drying activities in some areas. Authorities have additionally issued flood warnings.
Both Arabica and Robusta harvests are underway. In the western region, harvesting is reaching its peak in the Rwenzori Mountains. In eastern Uganda, the crop is approaching its peak, while harvesting around Mount Elgon is already well advanced, having started approximately a month earlier.
Coffee flows are gradually improving as the harvest progresses, with consistent volumes arriving in Kampala.
Differentials for both Arabica and Robusta continue to be firm. Meanwhile, the Ugandan Shilling has depreciated sharply against the US dollar over the past two weeks.
There are no significant updates regarding logistics.